
How share buybacks can raise EPS without increasing total earnings
Double-digit EPS growth with little change in total earnings may reflect buybacks reducing the share count. Inspect both numerator and denominator.
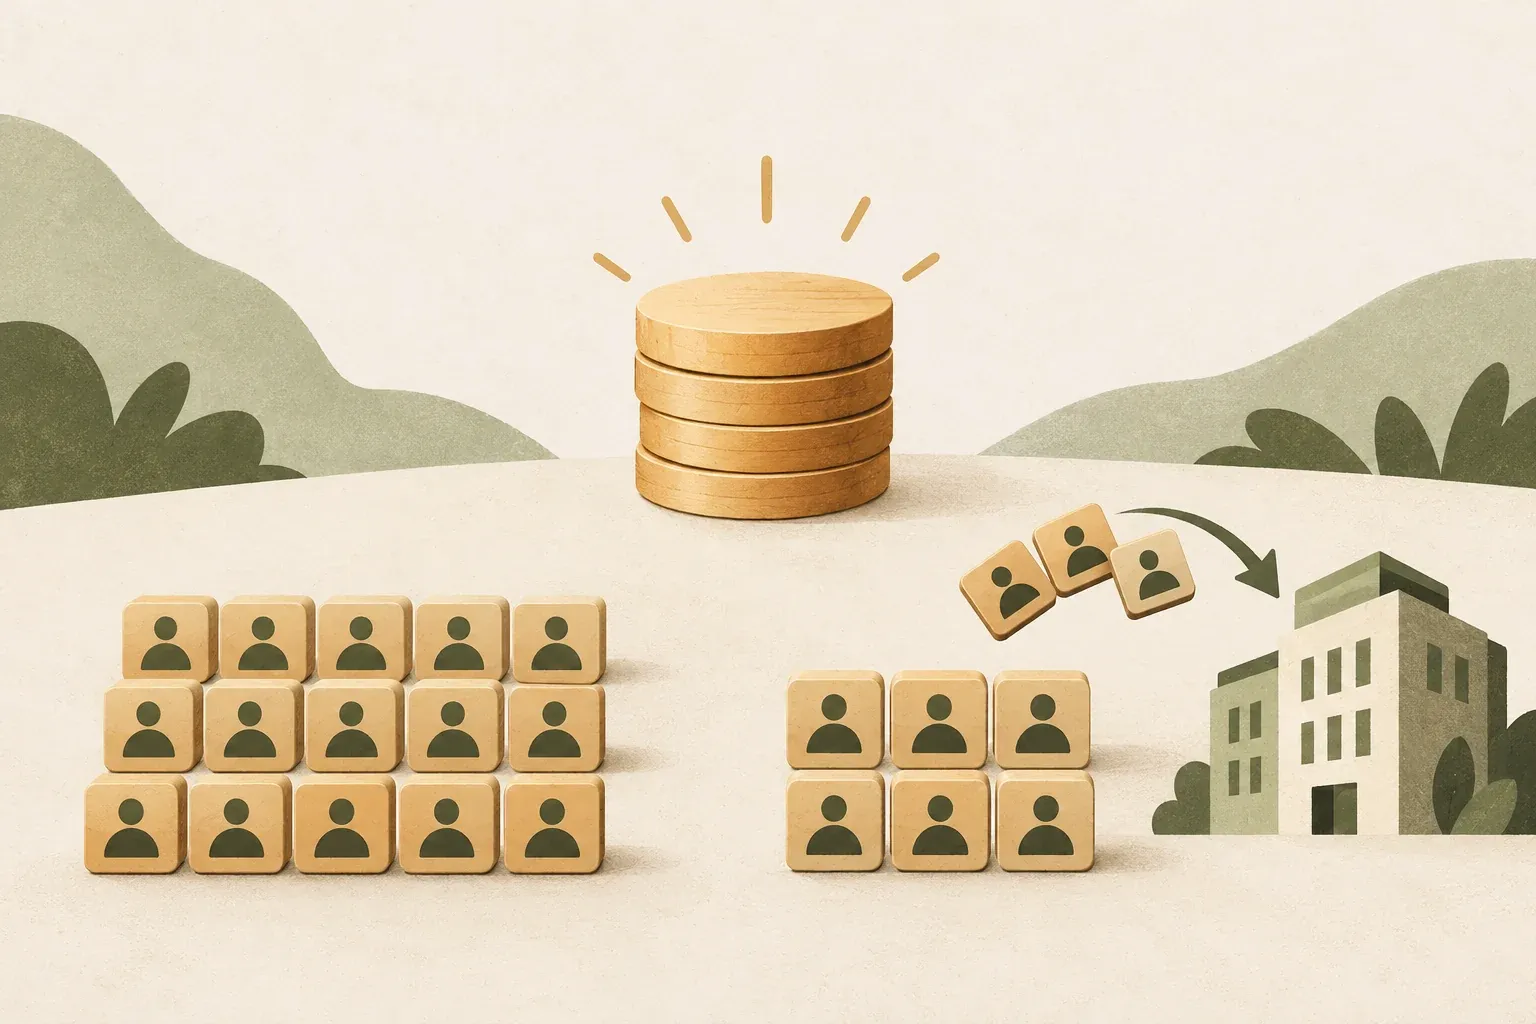
Share buybacks can raise EPS even when total earnings stay unchanged
EPS, or earnings per share, is profit attributable to common shareholders divided by the weighted-average number of common shares used in the calculation. If a company buys back stock and the number of shares counted in the divisor decreases, EPS may increase without net income increasing at all. This is why you shouldn't read news about "EPS growth" and immediately conclude that business sales are improving.
A share repurchase, or buyback, is a company buying its own shares. EPS calculation principles from IFRS Foundation on IAS 33 and notes to actual financial statements in the database SEC EDGAR explain the EPS denominator and show why repurchases and weighted-average shares are separate figures to read together.
Read both the numerator and denominator in full
For a simple explanation, assume no preferred shares or other earnings adjustments. The basic formula is:
Basic EPS = Net profit attributable to common shareholders ÷ Weighted average number of common shares during the period.
Timing matters: shares repurchased midyear remain in the weighted-average denominator for the time they were outstanding. The first example assumes the buyback finishes before the comparison year begins to isolate share-count effects.
Hypothetical example: EPS increases 11.1% without increasing profits.
Suppose Company A reports in United States Dollar (USD) and equal annual net income of $100 million in both years, with no new or preferred shares and excluding financing costs or cash opportunity costs. A buyback of 10 million shares before year two leaves 90 million denominator shares throughout that year.
| items | First year | Second year |
|---|---|---|
| Net Profit (Million USD) | 100 | 100 |
| Weighted-average common shares (millions) | 100 | 90 |
| Basic EPS (USD/share) | 100 ÷ 100 = 1.00 | 100 ÷ 90 ≈ 1.11 |
| Change in EPS | Comparative base | About +11.1% |
Check it yourself: (100 ÷ 90) ÷ (100 ÷ 100) − 1 = 0.1111, or approximately 11.1%. These figures are entirely hypothetical, not actual company data or forecasts. Repurchasing 10 million shares at US$20 requires US$200 million before related costs. That cash is not free and may have alternative uses.
The cited SEC example covers the fiscal year ending February 1, 2025, solely to locate buyback and basic/diluted EPS tables. It does not claim that company has constant profits like hypothetical company A. IAS 33 does not replace every US accounting requirement.
Midyear buybacks require weighted-average shares, not year-end shares
In another example, annual profit remains $100 million, with 100 million shares in the first half and 90 million in the second. Assuming equal periods and no other changes, the simple weighted average is (100 × 0.5) + (90 × 0.5) = 95 million shares, giving EPS of about 100 ÷ 95 = $1.05 per share, rather than 1.11 dollars.
Actual reports also require diluted weighted-average shares, potentially including options or conditional equity awards. Diluted EPS has additional rules; do not simply add every potential future share. See basic/diluted examples in Financial statement notes filed with the SEC
How to read actual reports without being misled by rising EPS
Now vary both earnings and shares: net income falls from US$100 million to US$95 million while weighted-average shares fall from 100 million to 90 million. EPS becomes 95 ÷ 90 ≈ 1.0556 dollars, about 5.56% above the US$1 starting EPS despite a 5% decline in total earnings. Calculate from unrounded values and round the percentage to two decimals. This does not identify why earnings fell or establish whether the buyback created value.
- Start with net income: Compare revenue, margins, and net income with previous periods; do not read EPS in isolation
- Check weighted-average shares: Find basic and diluted weighted-average shares outstanding in the financial statement notes
- See buybacks: Check the share count, average purchase price, and cash spent in the repurchase disclosures, cash flow statement, or related notes.
- See the source of funds: Did the company use surplus business cash or take on more debt? Review debt, interest, and remaining cash.
- Ask whether the returns justify the risk: Mathematically higher EPS does not confirm that the price at which a company is buying back shares is appropriate.
For cross-company comparisons, check simultaneous employee share issuance or capital raising, which can offset buybacks, and match the data periods.
Limitations: EPS growth does not necessarily mean the company's value has grown equally.
Buybacks may return capital to selling shareholders and reduce shares outstanding. The cash spent also reduces company assets. Borrowing to fund repurchases may add interest costs and risk. Market prices depend on expectations, risk, and other factors, so they do not always change in proportion to EPS.
Across periods, also examine unusual items, accounting policies, and diluted shares. Buyback authorization is not proof of completed repurchases; verify actual purchases and cash spent.
Before accepting EPS growth, separate business performance from share-count effects
Before assessing EPS growth, check whether total profit grew, how much the weighted-average share count fell, and where the company obtained the money for repurchases. These answers help distinguish business performance from changes in the share-count denominator. This article provides general education, not a recommendation to buy or sell shares.
Sources
- IFRS Foundation: IAS 33 Earnings per Share
- SEC EDGAR: Capital Stock and Earnings Per Share (Tables), fiscal year ended February 1, 2025
For education only, not personalized investment advice. All company A figures are hypothetical, assuming earnings and other factors remain unchanged.